
Bridge Financing in Ontario
Bridge financing in Toronto, the GTA and across Ontario. Buy your next home before your current one closes. Karla Badillo, Mortgage Broker, FSRA #12176, Sherwood Mortgage Group.
Explore Your Bridge Financing Options
Bridge financing is designed for homeowners bridging the timing between a home purchase and sale. Subject to lender qualification and approval.
Over 100 Lenders
Bridge Financing That Lets You Buy Before You Sell
Buying your next home before your current one sells can feel overwhelming. When your closing dates do not line up, bridge financing may help you move without rushing your sale or risking your purchase. It is a short-term loan that covers the gap between buying your next home and closing the sale of your current one, letting you take possession of the new place before the money from your sale lands. The loan is secured against your existing home and repaid the moment that sale completes.
If your purchase closes before your sale, Karla Badillo bridge financing service can help you understand your options and identify the right path forward. She helps Ontario homeowners understand whether bridge financing is the right solution for their purchase and sale timeline, comparing multiple lenders to find suitable options.
More lenders. More options. One mortgage strategy built around you.
- Access to 50+ Canadian Lenders
- Fast Approvals Available*
- Funding in as Little as a Few Days*
- 13+ Years Helping Ontario Homeowners
What Is Bridge Financing
A Short-Term Loan That Covers the Gap Between Two Closings
So what is bridge financing in plain terms? It is a short-term loan that gives you access to your existing home’s equity before that home actually sells. You use it to fund the down payment or the full purchase of your next place, then pay it back in full when your sale closes. Because it is short and secure, it is one of the more predictable tools in a move.
How much you can bridge depends on your existing home’s equity, your sale details and the lending guidelines that apply to your file. Karla walks that math with you so the two dates fit together cleanly.
How a Bridge Financing Loan Works
A bridge financing loan works off the equity in the home you are selling, usually requiring an unconditional sale agreement before a lender will fund it. The lender advances the funds you need for the new purchase, then registers the bridge against your existing property. When your sale closes, the bridge is repaid in full, often within a few weeks.
Something most people do not realize until they are in it: many lenders charge bridge interest daily, so a closing that slips by even a few days changes the final cost. Karla will show you exactly what the bridge costs against the convenience it buys.
Is Bridge Financing Worth It?
That usually comes down to your two closing dates and your peace of mind. When your purchase closes days or weeks before your sale, a bridge removes the need to delay possession, rush your buyer or scramble for temporary housing. For most movers in that spot, the short interest cost is well worth avoiding the chaos.
It is less useful when your sale has not firmed up, because most lenders want an unconditional sale before they fund a bridge. A bridge financing program is built around certainty, not hope.
Benefits of Bridge Financing
- Buy before your current home sells
- Avoid rushed closings
- Access your equity sooner
- Reduce moving stress
- More lender options through one broker
- Personal guidance from start to finish
Let's See What’s Possible
Every day your closing dates move closer. Waiting too long can leave you scrambling for financing or even put your purchase at risk. Karla reviews your timeline, equity and lender options so you know exactly what’s possible before closing day arrives.
How can Karla help?
- Cover the gap between your purchase and your sale
- Free up your down payment before your sale closes
- Avoid a rushed same-day closing
- Explore bridge financing options for a tight timeline
- Compare a bridge loan against other short-term routes like a second mortgage or refinancing
- Look at bridging finance for bad credit situations
- Line up bridge financing across Toronto, Vaughan, Richmond Hill, Markham, Mississauga, Brampton, Oakville, Burlington and Hamilton
Mortgage Advice That Puts Clients First
See what homebuyers and homeowners have said about Karla’s communication, guidance and commitment to helping them understand their mortgage options.

Karla is amazing at what she does and is able to provide solutions that fit everyone. Karla is very knowledgeable and helpful when it comes time to secure a good mortgage with a good rate. My husband and I really appreciate everything that Karla has done for us and couldn’t have asked for a better experience. Karla is always available for questions and provides excellent customer service every step of the way. Thank you Karla!

I’m impressed with your level of professionalism and comprehension of your client needs. I have worked with many other brokers and one way or another they always made me feel they were working for their commission and not with their client needs. Thank you very much for your time and the services you provided me and my wife. Will definitely recommend you with my friends and network

As first-time home buyers, we learned the importance of having the best mortgage agent on our side! Karla Badillo found us a great interest rate for our mortgage, better than banks were offering us. Our credit score wasn’t great, but she worked on other possibilities to make our credit improve. During the process, we had endless questions, but she was available via email, phone, or WhatsApp to guide us and answer each one. Thank you, Karla Badillo for all your help and hard work. You made our dream came true!

Understanding Bridge Loan Costs
A bridge loan can affect your closing timeline, your cash flow and how smoothly your move goes. Karla looks past the rate on its own and helps you understand the complete picture.
- Bridge loan interest rates are typically higher than standard mortgage rates
- Interest is calculated daily based on your outstanding balance
- You pay interest only for the days your bridge loan is outstanding
- Your total cost depends on your loan amount and the gap between your two closing dates
- Many lenders charge a modest administration or setup fee on top of the interest
- A shorter gap generally means a lower total cost
In some cases a home equity loan or a private mortgage may be a better fit than bridge financing. Karla will tell you straight if a bridge is the wrong tool for your situation.

Bridge Loan Cost Calculator
Wondering what bridge financing could cost? Use our calculator to estimate your interest based on your loan amount and the number of days between closings.
One of the biggest surprises Karla sees is buyers assuming the bridge amount is simply their down payment. In reality, the available bridge is calculated from your sale proceeds, your mortgage payout, the fees and the timing between closings. That is usually a smaller and more specific number than people expect, which is exactly why a five-minute conversation beats guessing off a calculator.
Bridge Financing vs. Second Mortgage vs. Refinancing
| Feature | Bridge Financing | Second Mortgage | Refinancing |
|---|---|---|---|
| Purpose | Cover the gap between two closings | Access equity while keeping your first mortgage | Replace your mortgage at a new rate or higher amount |
| Typical Term | Days to weeks | 1 to 5 years | Full new mortgage term |
| Repayment | Paid in full when your sale closes | Monthly payments alongside your first mortgage | Monthly payments on the new mortgage |
| Key Requirement | Unconditional sale on your current home | Sufficient equity in your property | Sufficient equity and income qualification |
| Best Fit | Your purchase closes before your sale | You need funds now but want to keep your current rate | You want a better rate or need to pull out a larger amount |
Not sure which option fits? Karla can walk you through the differences based on your timeline and financial goals. A second mortgage or refinancing may work better depending on your situation.
Knowing Which Lender to Approach Is Most of the Job
Banks will offer a bridge to strong files, but they are not the only place these loans come from. Below the banks sit credit unions, alternative lenders and private lenders, each with their own lending box. One will bridge a long gap that another will not touch.
Homeowners across Mississauga, Brampton and Oakville often start at their bank and hear no before discovering there are other options. Karla has spent years building lender relationships, so your deal goes to the right desk the first time. She will tell you straight if the answer looks like no across the board.
Karla reaches lenders who do not deal with the public directly, which matters most when your closings are tight. That access does not mean approval for everyone, but it does mean more doors than a single branch can open. One lender’s no is not the final answer.
Karla Would Rather Lose a Deal Than Put You in a Bridge That Does Not Fit
A bridge only works when your sale is unconditional and your two closings genuinely overlap. If the sale is still conditional, most lenders will not fund, and forcing it creates more risk than it removes. Karla will be honest about one thing: does your timeline actually call for a bridge.
There is also the matter of the gap length, because a short overlap is cheap while a long or uncertain one costs more and carries more risk. The bridge should be a clean, short tool, not an open-ended loan. Karla builds that clarity into the plan from the start.
- Is your sale unconditional
- How many days are actually between your two closings
- Do you have enough equity to support the bridge
- What happens if your sale closing gets delayed
- Is a bridge the right tool, or would a home equity loan or private mortgage fit better
A good bridge is short, clean and repaid the day your sale closes. Karla keeps it that simple whenever the file allows.
Declined by Your Bank? You May Still Have Options
A bank’s decision is based on its own lending guidelines, but those guidelines vary from lender to lender. Getting a no from one bank is not necessarily the final answer. An experienced broker like Karla can present your application to multiple lenders to find one that fits your situation. One lender’s no could be another lender’s yes.

Quick note: All mortgages remain subject to lender qualification and approval.
What Happens Without Bridge Financing?
- You might have to request an extension on your purchase closing date
- The seller could refuse to extend, putting your purchase at risk
- You may need to find temporary accommodations between closings
- You might resort to higher-cost financing like a private mortgage
Meet Karla Badillo
Mortgage Guidance Built Around Real People and Real Financial Goals
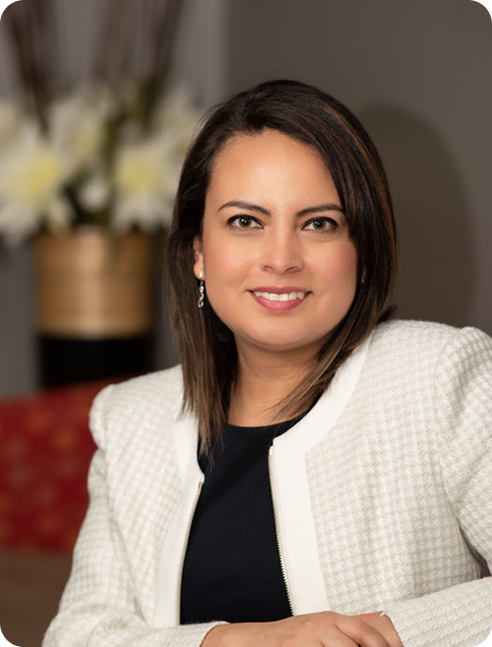
Karla believes that a move should start with a conversation, not a scramble. She started her career as a financial advisor, which taught her to plan for clients over both the short and long term. That planning mindset is exactly what a bridge needs, because timing and certainty are everything.
With over 13 years in the mortgage industry, Karla Badillo has worked closely with clients across Toronto, Vaughan, Markham, Richmond Hill, Burlington, Hamilton and communities throughout Ontario to line up smooth moves. If your purchase closes before your sale, she will provide clear explanations and personal guidance throughout the process. You will get honest communication, responsive service and a strategy built around your goals.
A Simpler Way to Explore Your Refinancing Options
Step 1. Tell Karla What You Want to Accomplish
Complete the secure application or start with a brief conversation about your purchase, your sale and your closing dates. Karla listens first, then maps the options that actually fit.
Step 2. Review the Available Lending Paths
Karla will assess the file and identify suitable bridge options through her lender network. She will explain the rates, fees, term and repayment trigger attached to each option.
Step 3. Move Forward With Confidence
Once you choose the right solution, Karla will coordinate the application, documentation and lender requirements. She keeps you informed through approval, legal and closing.

Plan Your Mortgage with Karla’s Free App
Estimate your mortgage payments, explore how much you may qualify for and calculate potential closing costs—all conveniently from your phone.
Karla Does More Than Bridge Financing
Karla Badillo Bridge Financing is one part of a full set of financing solutions for Ontario homeowners. Whatever the goal, there is usually more than one way to get there.

Find Out If Bridge Financing Is Right for Your Timeline
A quick conversation could help you avoid unnecessary costs, delays or last-minute financing surprises.
One lender’s no is not the final answer.
Speak directly with Karla Badillo and receive a clear review of your options.
Rates, terms and approvals are subject to lender qualification and may change without notice. Additional lender, legal, appraisal or brokerage fees may apply depending on the mortgage product and application.
FREQUENTLY ASKED QUESTIONS
More general questions are answered on the main FAQ page. The answers below focus on bridge financing specifically.
What is bridge financing in simple terms?
Bridge financing is a short-term loan that covers the gap between buying your next home and closing the sale of your current one. It lets you access your existing home’s equity before that home actually sells. You repay it in full when your sale closes, usually within a few weeks. Most movers use it to avoid a rushed same-day closing.
How much can I bridge in Ontario?
The amount depends on the equity in the home you are selling, your sale details and the lender’s guidelines. Lenders generally bridge the shortfall you need for your new purchase, backed by your sale. A bridge financing calculator gives you a rough sense of the interest. Only a full review gives you a real number, subject to lender qualification and approval.
Do I need a firm sale to get a bridge?
Usually, yes. Most lenders require an unconditional sale agreement on your current home before funding a bridge. The sale is the lender’s main security and the source of repayment. Without it, a bank will usually decline, though some alternative or private lenders may consider applications without a firm sale, depending on the available equity and the overall strength of the file. Karla can tell you what your specific file needs.
Is bridge financing worth it?
Often, yes. When your purchase closes before your sale, a bridge removes the need to delay possession or scramble for housing, and the short interest cost is usually small next to that convenience. It is less useful when your sale is not yet unconditional. Karla will run the numbers so you can decide with real figures.
Can I get bridge financing with bad credit?
Possibly. Bridging finance for bad credit may still work when your sale is unconditional and your equity is strong, because the sale is the lender’s main security. The rate will be higher and the plan has to make sense. Karla can tell you quickly if it is realistic for your file.
What does a bridge loan cost?
The bridge financing cost is usually interest for the days you use the funds, plus a modest lender or administration fee. Because you borrow for weeks rather than years, the total tends to be small next to a full mortgage. A longer or less certain gap can push it higher. Karla will lay out the full cost before you commit.
How long does a bridge loan last?
Most bridges are very short, often just the days or weeks between your two closings. They are repaid in full the moment your sale completes. Some lenders allow a longer bridge for a bigger gap. The right length depends entirely on your two closing dates.
Can I get bridge financing before my home is sold?
In most cases, bridge financing is approved with an unconditional sale on your current home. Some lenders may offer bridge loans without a sale agreement in place, especially if you have significant equity. The terms and rates may be less favourable compared to having a sale in place. If your home is not sold yet, give Karla a call to discuss your options.
Do all lenders offer bridge financing?
No, bridge financing is a specialized product that not all banks or lenders provide. Each lender has its own rules around the maximum bridge loan amount, loan-to-value limits and the maximum time they allow between closings. Working with a broker gives you access to more bridge loan options compared to going to a single bank.
Does submitting an application guarantee approval?
No. Every application is reviewed against the specific lender’s criteria, and outcomes depend on factors like your home equity, your sale status and other financial details. Submitting an application is the first step toward understanding your options, not a commitment from either side. All mortgages are subject to lender qualification and approval.
How quickly can bridge financing be approved?
Approval timelines vary by lender, but bridge financing can often be approved within a few business days when your documentation is complete and your home sale is unconditional. More complex applications may take longer.
What happens if my home sale is delayed?
If your home sale is delayed and the funds aren’t available before your bridge loan is due, your lender may charge additional interest until the loan is repaid. In some cases, you may need to request an extension of your bridge financing, but this isn’t automatic. Any extension is subject to your lender’s approval and may involve extra fees or updated conditions. If you learn your sale could be delayed, contact your mortgage broker immediately. The sooner they know, the more options they may have to work with your lender and help minimize disruptions to your purchase.